
LiveGexLevels Guide · Published
Positive gamma: what does it mean?
Near a level the price rises and someone sells, it falls and someone buys, and the swings get smaller. That someone is often a market maker who is long options and hedges his delta: positive gamma means he trades against the move, and the price tends to slow down.
 Watch on YouTube · 10:37
The other side
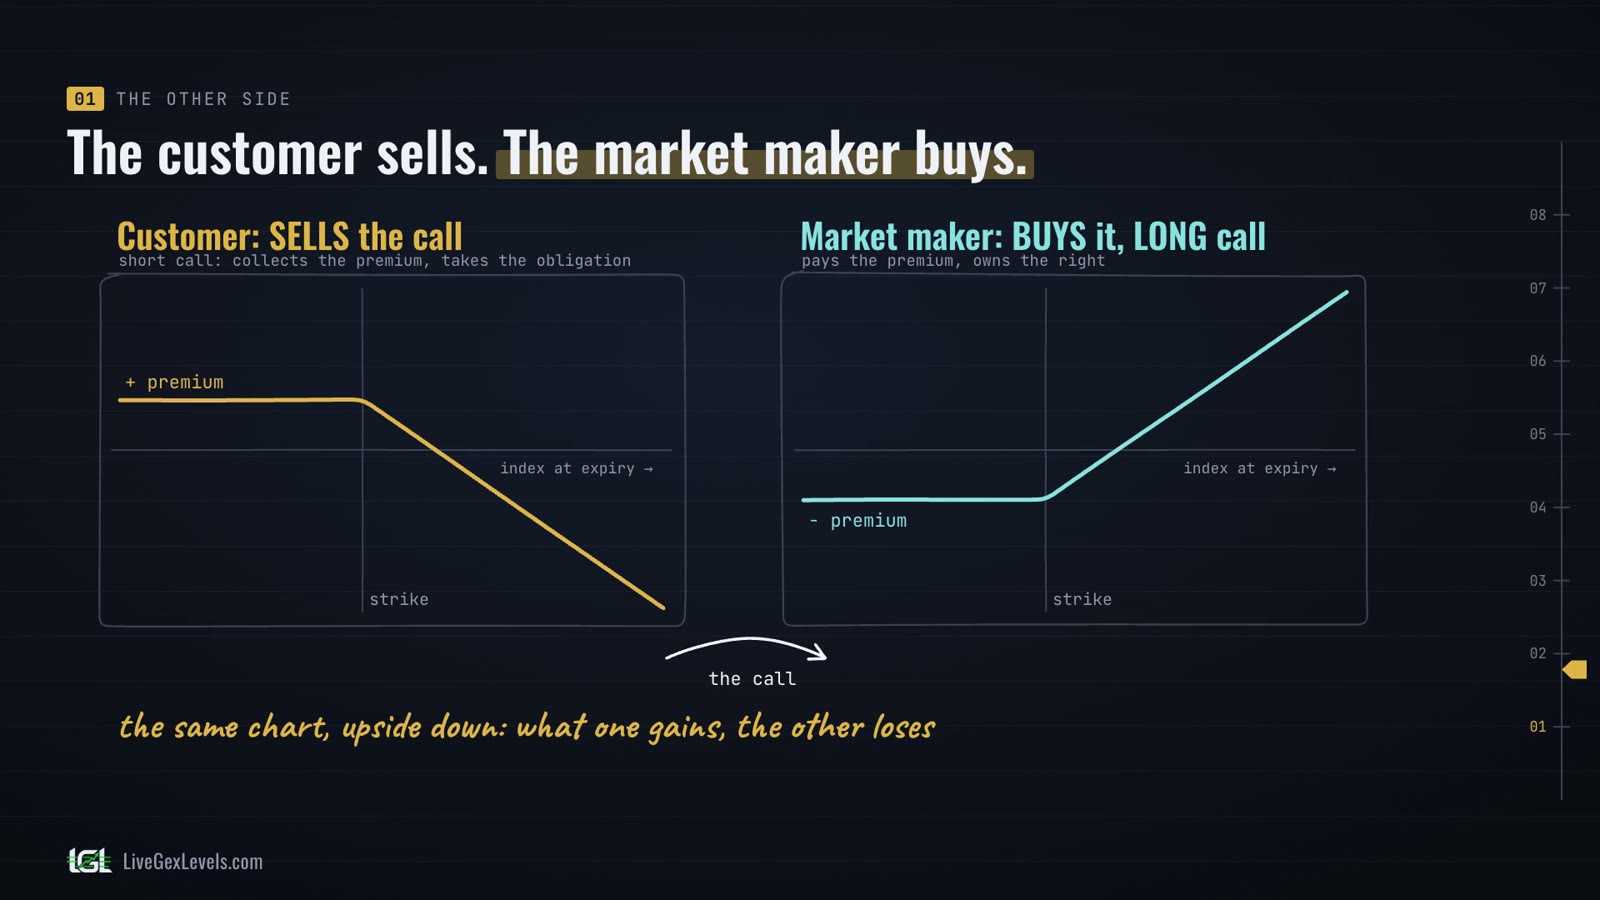
When a customer sells a call, someone buys it, and most of the time it's a market maker. Without market makers it would be very hard to find someone who takes the other side of your trade exactly when you want, at the strike and the expiry you choose. The market maker stands on the other side and keeps trades flowing: he makes the market, hence the name.
The customer sells: he collects the premium and takes on the obligation. The market maker buys: he is long the call, pays the premium and owns the right. At expiry the two payoffs are the same hockey stick, upside down: what one gains, the other loses.
The short call gets its own episode in Options School. Here, we follow the market maker.
The delta curve
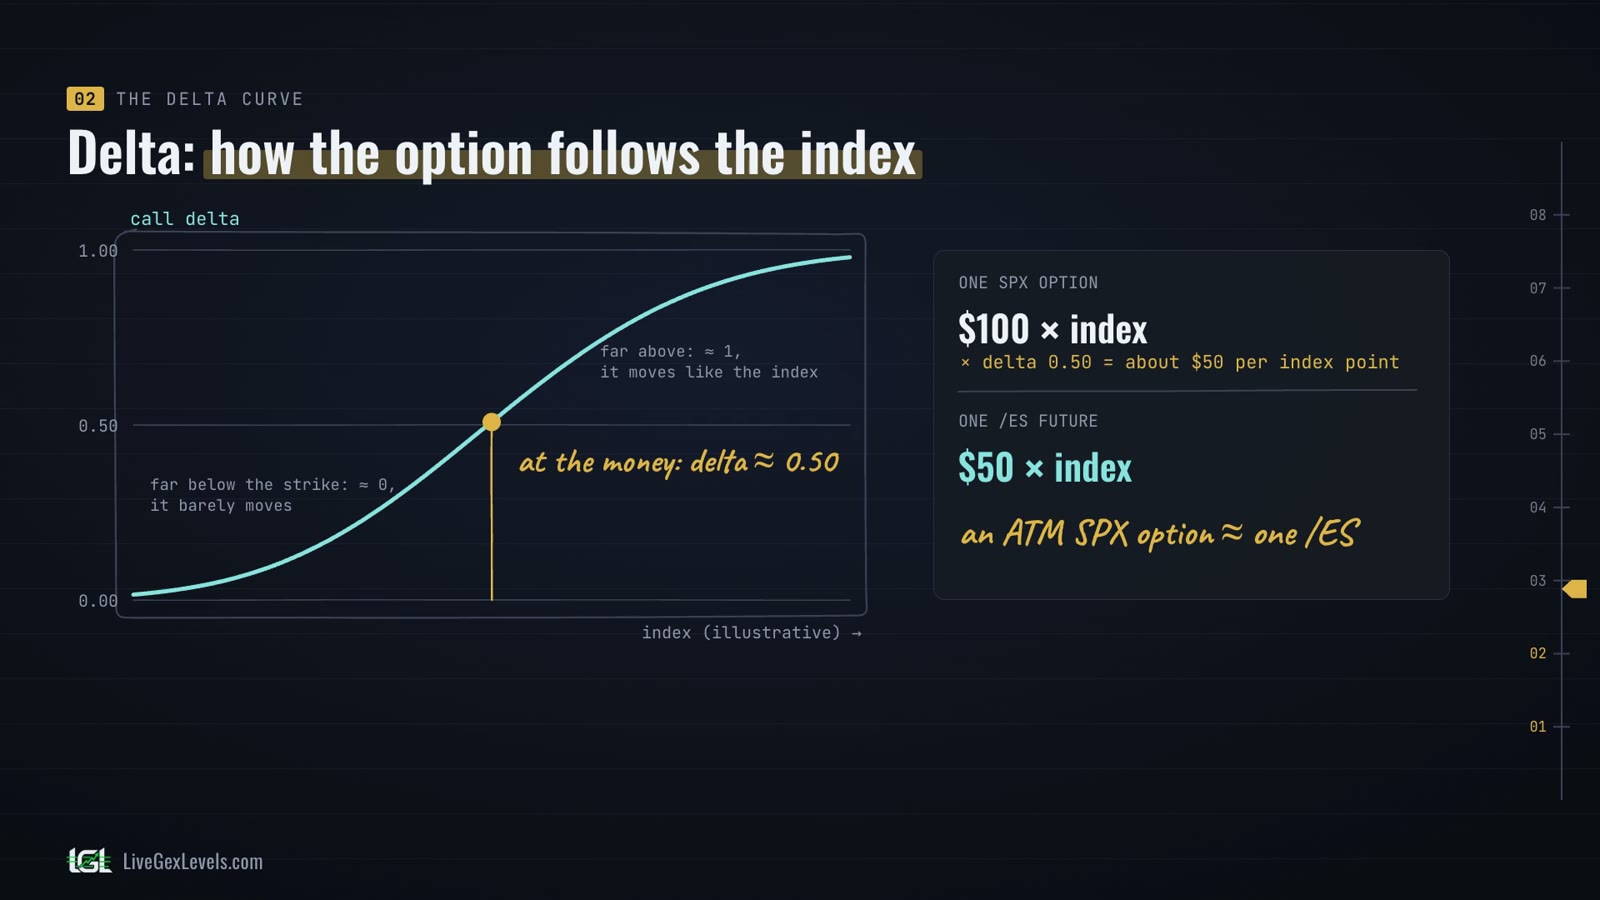
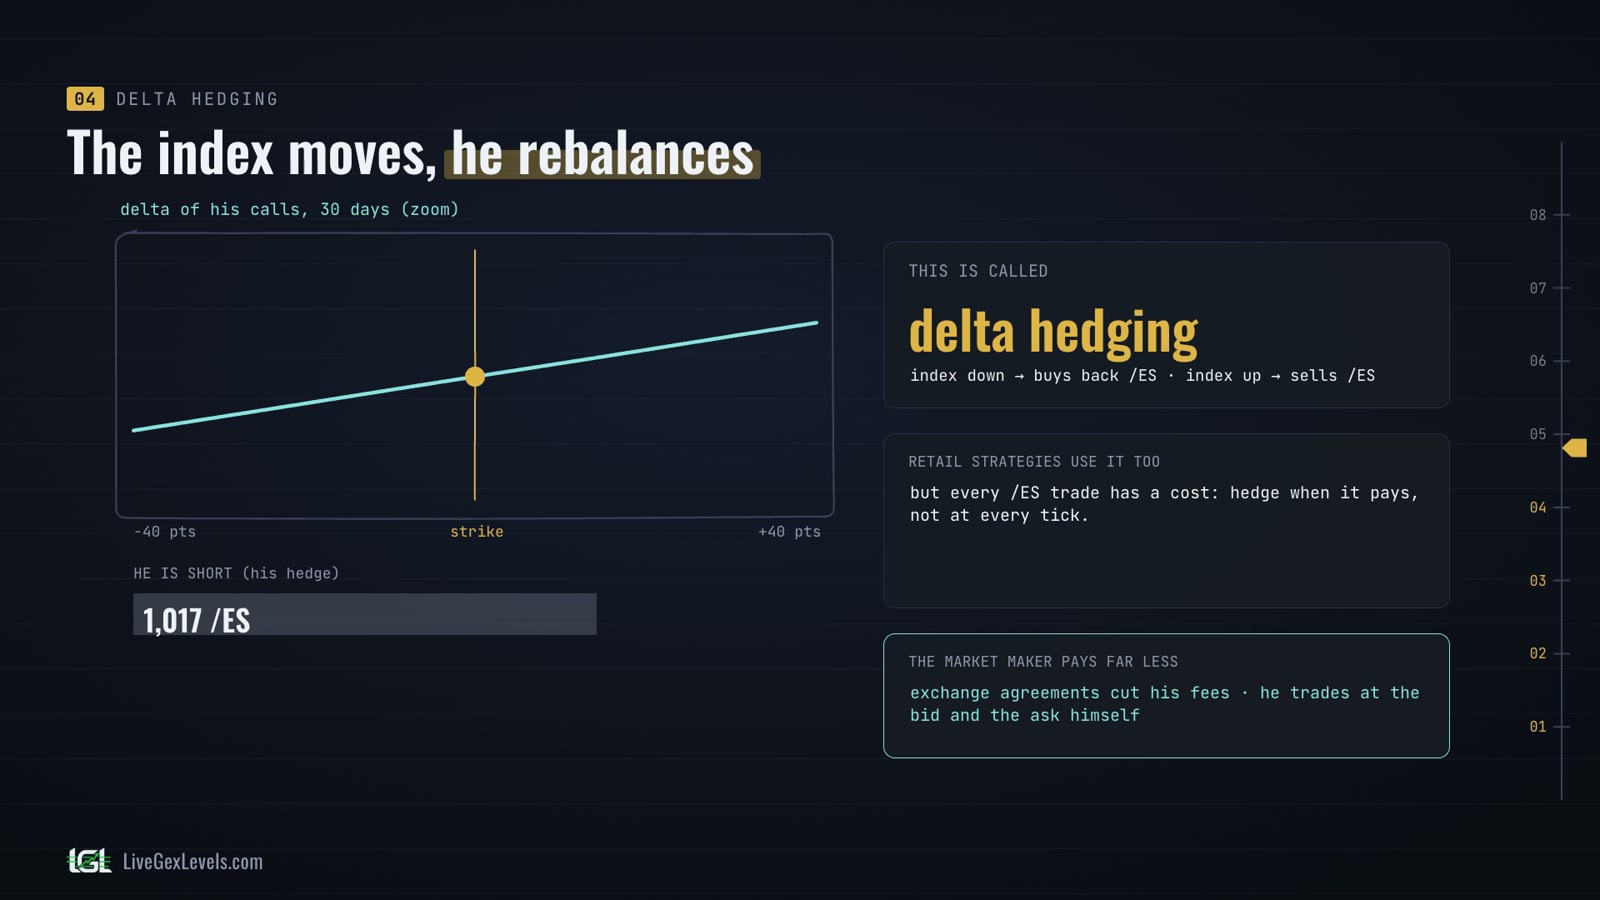
To hedge, he looks at one number: delta. Delta tells you how much the option moves when the index moves one point. Far below the strike, the call barely moves: delta is close to zero. Far above, it moves like the index: delta is close to one. At the money, right at the strike, delta is about a half.
Now a useful fact to remember. One SPX option is worth 100 dollars for each index point. With delta at one half, that's about 50 dollars a point. And one ES future is worth exactly 50 dollars a point. So one at-the-money SPX option moves about like one ES.
The hedge
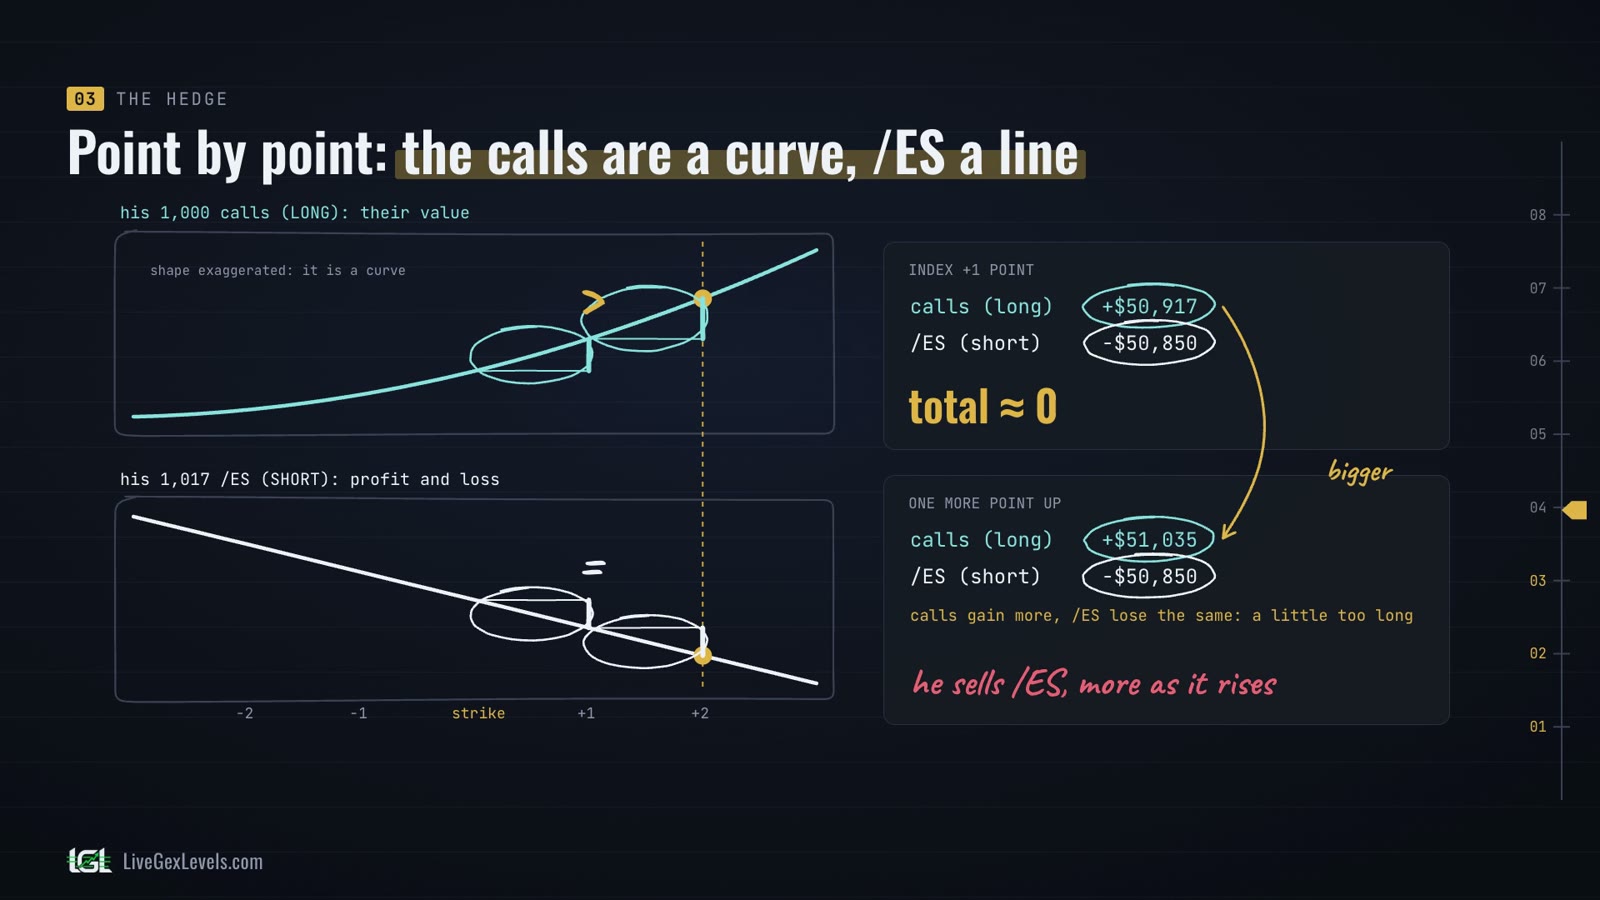
Customers sell 1,000 calls at the money, and the market maker buys them: he is long 1,000 calls. With delta at one half, it's as if he had bought about 1,000 ES. He gains if the index rises and loses if it falls. He doesn't want that bet: he earns on the spread, not on the direction. So he hedges right away by selling about 1,000 ES. Calls plus ES: net delta, zero.
Now move the index one point at a time. One point down: the calls lose about 50,800 dollars, and the ES he sold gain about the same. Total: about zero. That's how the protection works. But the balance changes as the price moves.
One more point down, and the calls lose a little less, because their delta has dropped, while the ES gain exactly the same as before. The calls are a curve; the ES are a straight line. Now he is a little too short. To keep the balance he closes some of his short ES, which means buying ES. And buying while the price falls slows the move down.
The other way works the same. One point up from the strike, the calls gain about as much as the ES lose. One more point up, the calls gain a little more and the ES lose the same. To stay balanced he has to sell ES, and the higher the price goes, the more he sells. Selling while the price rises slows it down as well.
Delta hedging
In motion: the index slips ten points, and he buys back about 24 ES. Another ten down, and he buys back again. It bounces, and he sells. It climbs above the strike, and he sells more. When it comes back down, he buys. Every time, against the move.
This is delta hedging: keeping the delta of the position close to zero by buying and selling the underlying as the price moves. Retail traders use it too, in some option strategies. But for them every ES trade has a cost, so they hedge when it pays, not at every tick.
The market maker is in a different position. As a liquidity provider, he usually has agreements with the exchanges that cut his fees, and he trades close to the bid and the ask himself. So hedging costs him far less than it costs a retail trader. Later videos look at strategies that collect time value while hedging their delta, and at the risk that remains when the price moves a lot.
Near expiry
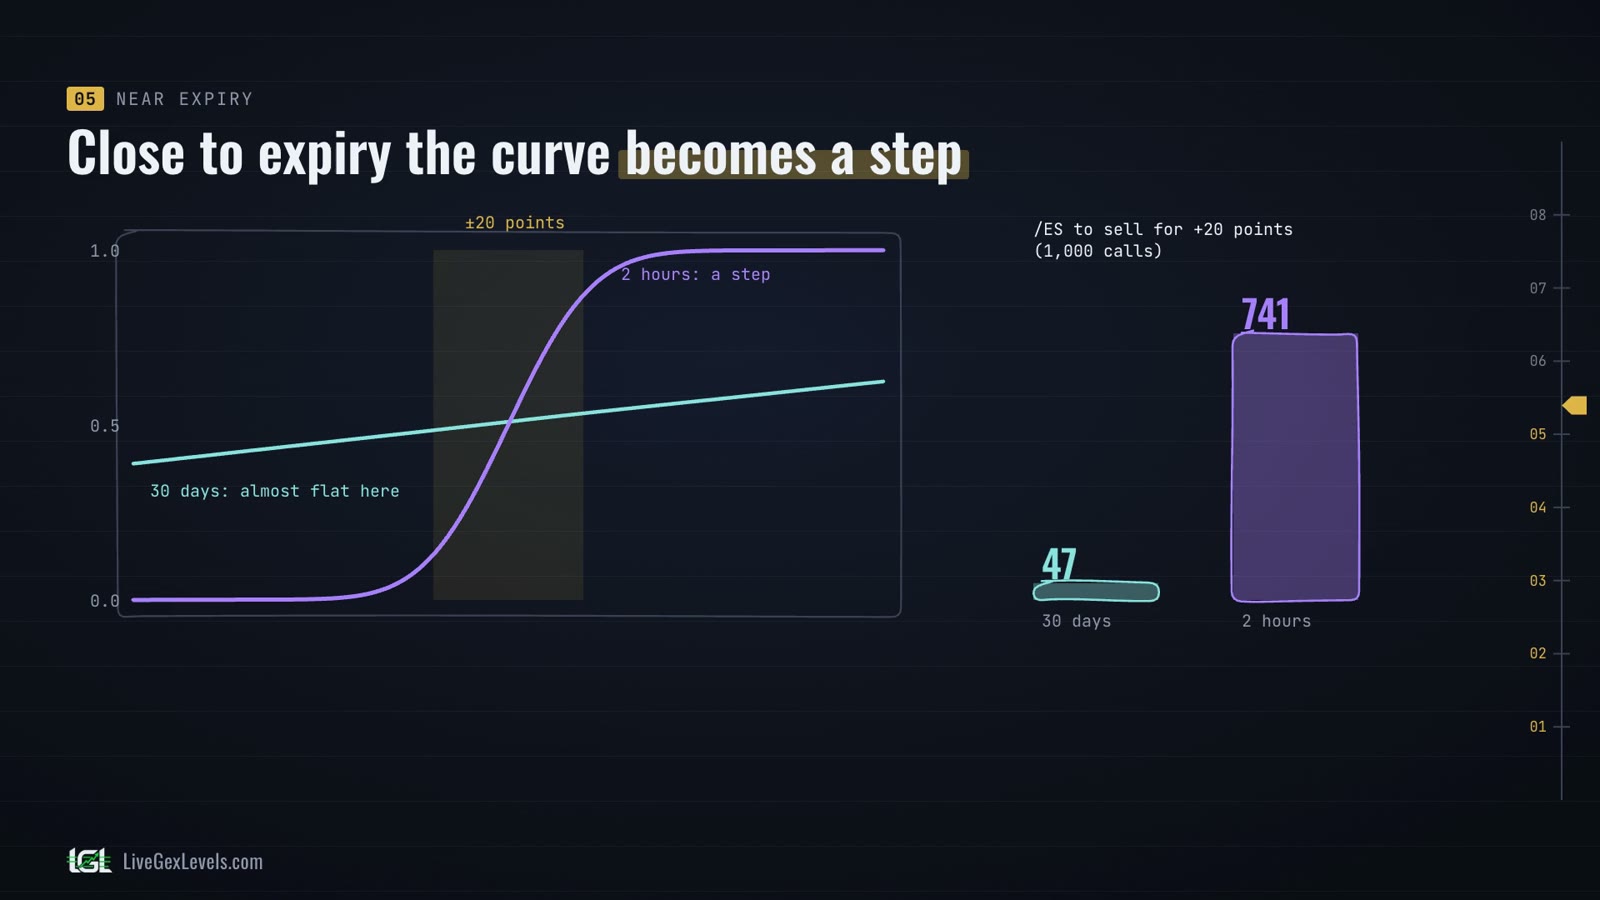
Now bring everything close to expiry, with the same option and the same strike. Thirty days out, the delta curve is soft, spread over hundreds of points. Two hours before expiry, it becomes a step: from almost zero to almost one, within a few dozen points.
For the same twenty-point rise, his 1,000 calls need 47 ES sold at thirty days, and 741 at two hours: about sixteen times as much. That's gamma: how fast delta changes, the slope of the delta curve.
So the same game, two hours from expiry, moves hundreds of ES every five points, right around the strike; thirty days out it was about a dozen. The small adjustments become real flows. That's why the options closest to expiry, the ones expiring today or tomorrow, weigh the most on the moves of the underlying: per contract, near the strike, their hedging is many times larger. And the strikes with the heaviest positions turn into levels the price can feel.
The whole book
Of course, a market maker doesn't hedge one call at a time. He holds thousands of positions, on many strikes and expiry dates, calls and puts, some long and some short. Deltas add up, so he nets them all into one delta for the whole book and hedges it in steps, mostly with ES, thousands at a time.
Gamma he watches expiry by expiry, because the closest expiries change the fastest. The Greeks get their own episodes in Options School: here, the idea is enough.
Positive gamma
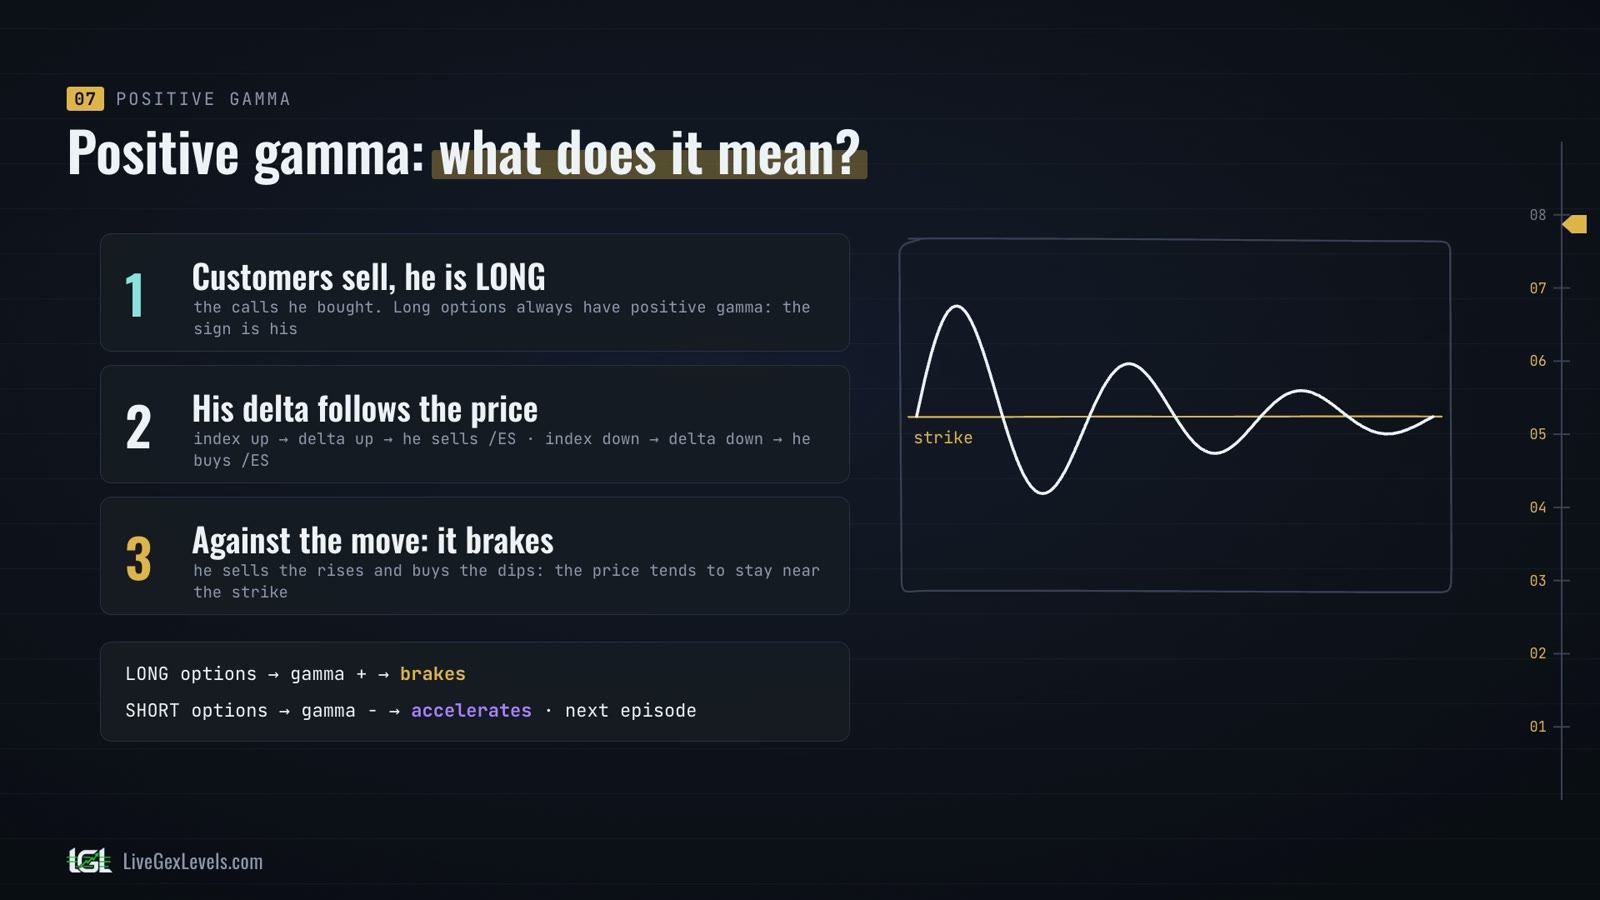
So, what does positive gamma mean? First: customers sold, so he is long the options. Long options always have positive gamma; short options have negative gamma. And the sign that matters is the market maker's.
Second: with positive gamma, his delta follows the price. The index rises, his delta rises, and he sells ES. The index falls, his delta falls, and he buys.
Third: he trades against the move. He sells the rises and buys the dips, so the price is braked and tends to stay near the strike. In the first episode we said dealers sometimes brake the price and sometimes amplify it: this is the brake.
If instead customers buy options, he is short, gamma is negative, and he has to chase the price, which amplifies it: that's the next episode. With positive gamma, levels tend to hold more.
In brief
- Customers sell the call; the market maker buys it, and is long.
- He hedges with ES, about one for each at-the-money SPX option, and keeps adjusting: he sells when the index rises and buys when it falls. That's delta hedging.
- Near expiry, the adjustments become large flows around the strikes.
- Long options mean positive gamma: the market maker trades against the move, and the price tends to slow down at the levels.
Sources
More from this series
Read next
See the levels live
Seeing where dealers have to hedge is information a chart alone doesn't give you. Your edge starts with preparation.
Card required; after the trial the subscription renews at the launch price. For educational purposes only, not financial advice.
