
Options School · Published
In, at or out of the money: sell or exercise?
Your call is in the money: do you exercise it or sell it? Before expiry, selling almost always beats exercising, because exercising throws the time value away.
 Watch on YouTube · 13:13
In, at or out of the money
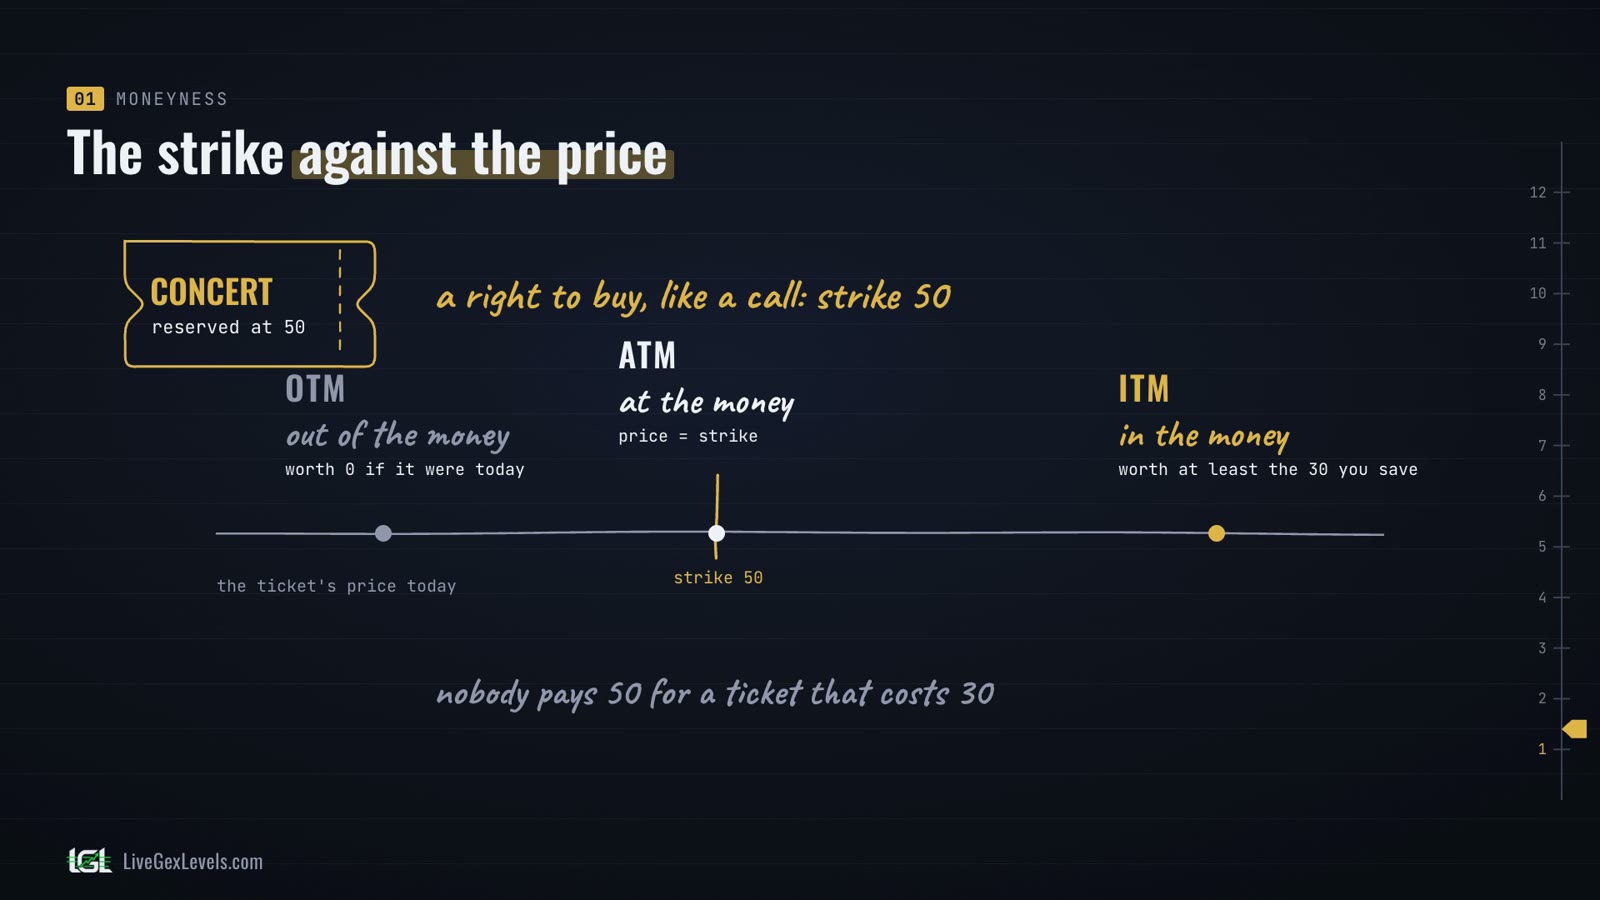
Start with something familiar. You've reserved a concert ticket at 50: until the concert you can pay 50 and collect it, or let it go. That's a right to buy, like a call, with a strike of 50.
If the ticket now sells for 80, your reservation is in the money: it's worth at least the 30 you'd save. At 50, it's at the money. At 30, it's out of the money: nobody pays 50 for a ticket that costs 30. ITM, ATM and OTM for short.
On an index the comparison is the same. With the index at 7,800, a call with strike 7,600 is in the money by 200 points. A detail rarely mentioned: a put with that same strike is out of the money, because it pays only below 7,600.
Those 200 points are intrinsic value, what the call would pay if it expired now. Yet the model prices it at 276: the other 76 are time value, the price of what can still happen. Time value peaks at the money, where the outcome is most uncertain: the 7,800 call is all time value, 148 points.
| Strike | Call price | Intrinsic value | Time value |
|---|---|---|---|
| 7,600 (ITM) | 276 | 200 | 76 |
| 7,800 (ATM) | 148 | 0 | 148 |
Buy, sell, exercise
An option has a price and can change hands. You can buy it: pay the premium to get the right. You can exercise it: use the right, buying or selling at the strike.
Selling means two things: closing an option you own, the subject here, or opening a new one on the side that carries the obligation. That's the short call, the next episode.
Can you exercise an option that's out of the money? You can ask your broker to, but it never pays: you'd buy above the market price with a call, or sell below it with a put. Only the automatic exercise at expiry is limited to options in the money.
American or European
The style decides when you can exercise. American: any trading day up to expiry. European: only at expiry. Options on stocks and on SPY, the ETF that tracks the S&P 500, are American; options on the SPX and XSP indices are European.
On the other side, when someone exercises, someone who sold that option is assigned and must honour the contract. That's assignment. Whoever sold an American option can be assigned before expiry; whoever sold a European one, only at expiry.
Sell or exercise?
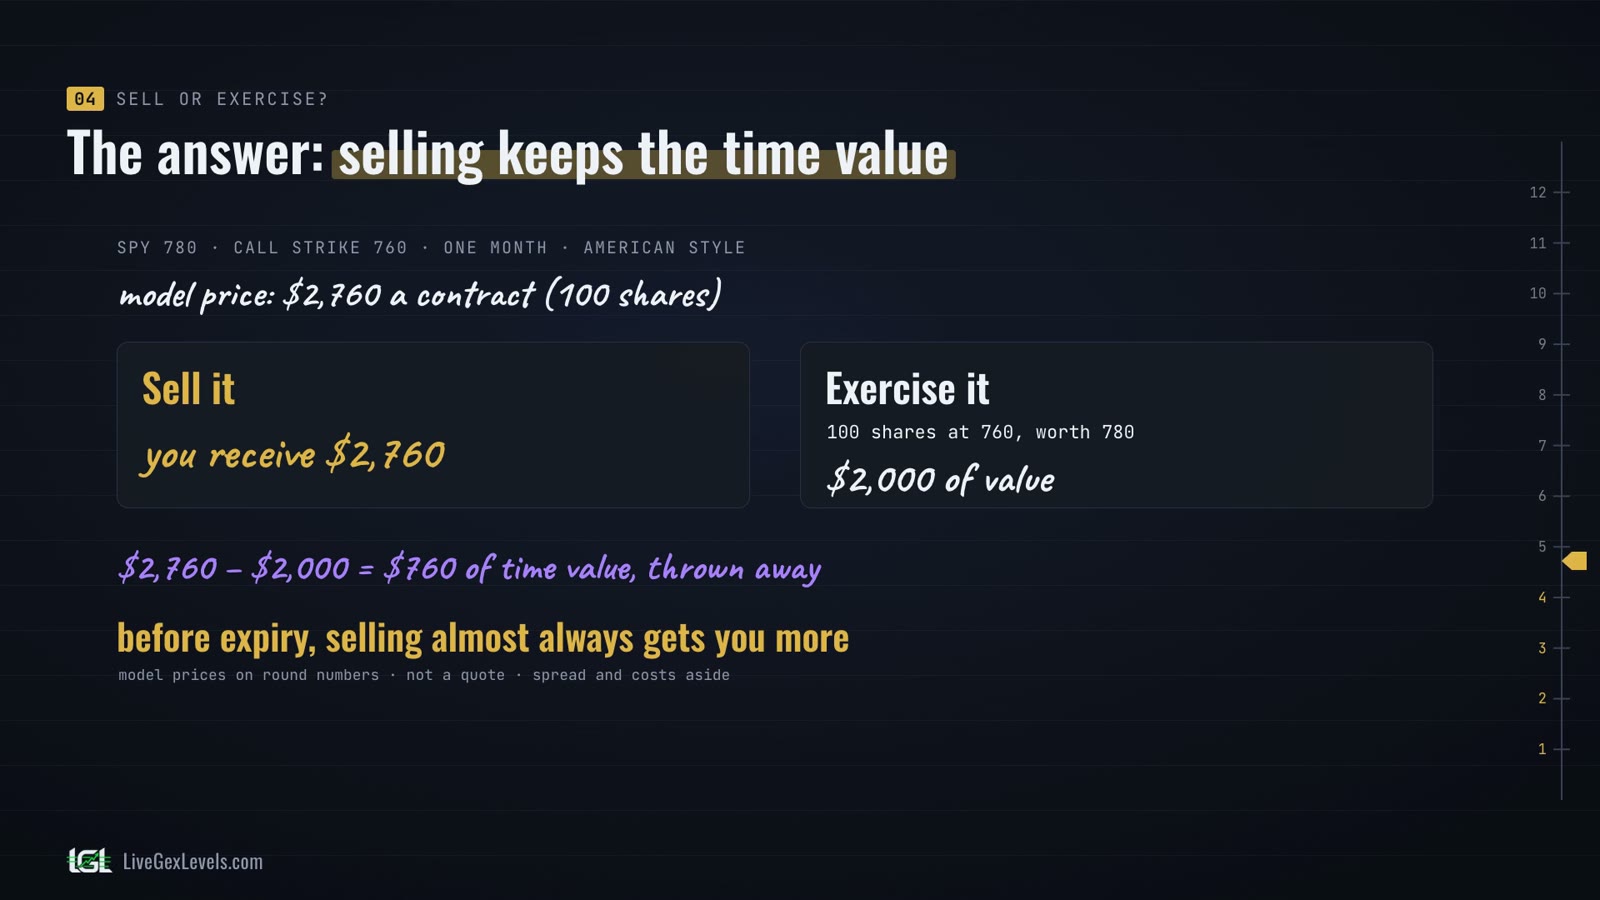
Now the opening question has an answer. Take an American call on SPY: SPY at 780, strike 760, a month to expiry. One contract is 100 shares, and the model prices it at 2,760 dollars.
Sell it, and you receive 2,760. Exercise it, and you buy 100 shares at 760 that are worth 780: 2,000 dollars of value. The difference, 760 dollars, was time value, and exercising throws it away. Before expiry, selling almost always gets you more.
One more cost to check: some brokers charge a fee to exercise or on assignment, sometimes above a normal commission; others charge nothing. It's in your broker's fee list.
What lands in your account
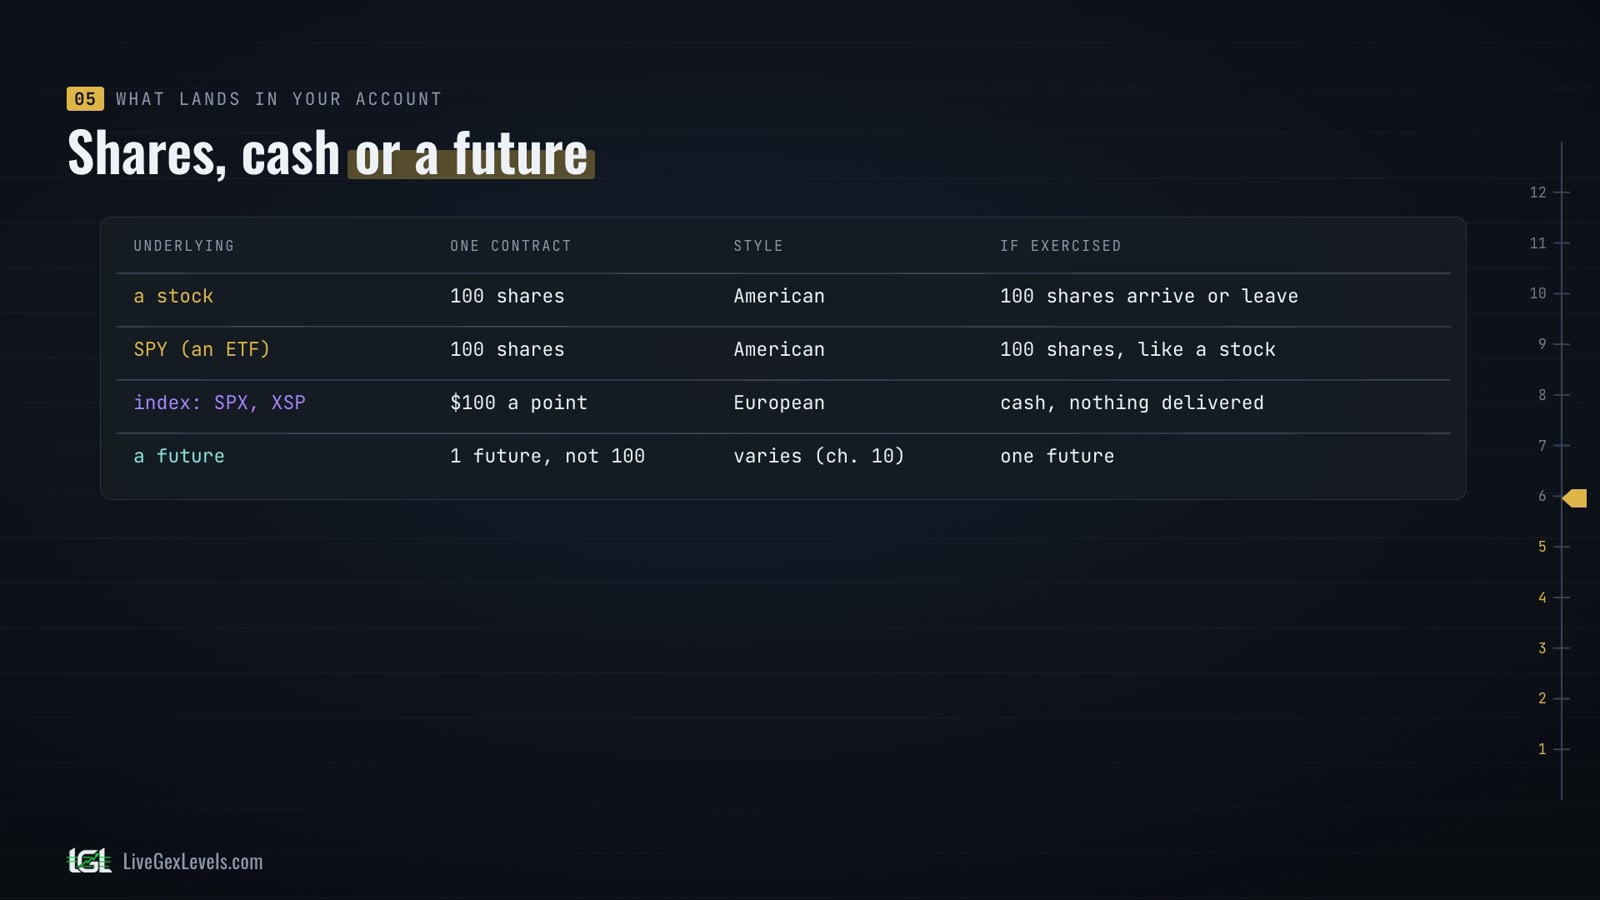
Exercise, or hold to expiry, and something lands in your account. On stocks, one contract is 100 shares. The official rules don't say why; the likely reason is history: 100 shares was the round lot, Wall Street's normal trading unit, and the first listed options, in Chicago in 1973, took that unit.
SPY is an ETF, but its options work like those on stocks: 100 shares, American style, shares delivered. Index options settle in cash: nothing to deliver. On futures, one option is one future, not 100.
Futures on goods: the delivery
That one future deserves a closer look. The S&P 500 future settles in cash, but many futures are on goods: oil, wheat, cocoa. An option on one of them gives you the future, and a future held into its delivery period can bring the goods themselves.
It has happened, on purpose: in July 2010 a London hedge fund, Armajaro, took delivery of about 240,000 tonnes of cocoa through the futures market, close to a billion dollars of beans, as the press reported at the time. A private account should avoid it, and many brokers close these positions, or ask you to, before delivery.
The buying power risk
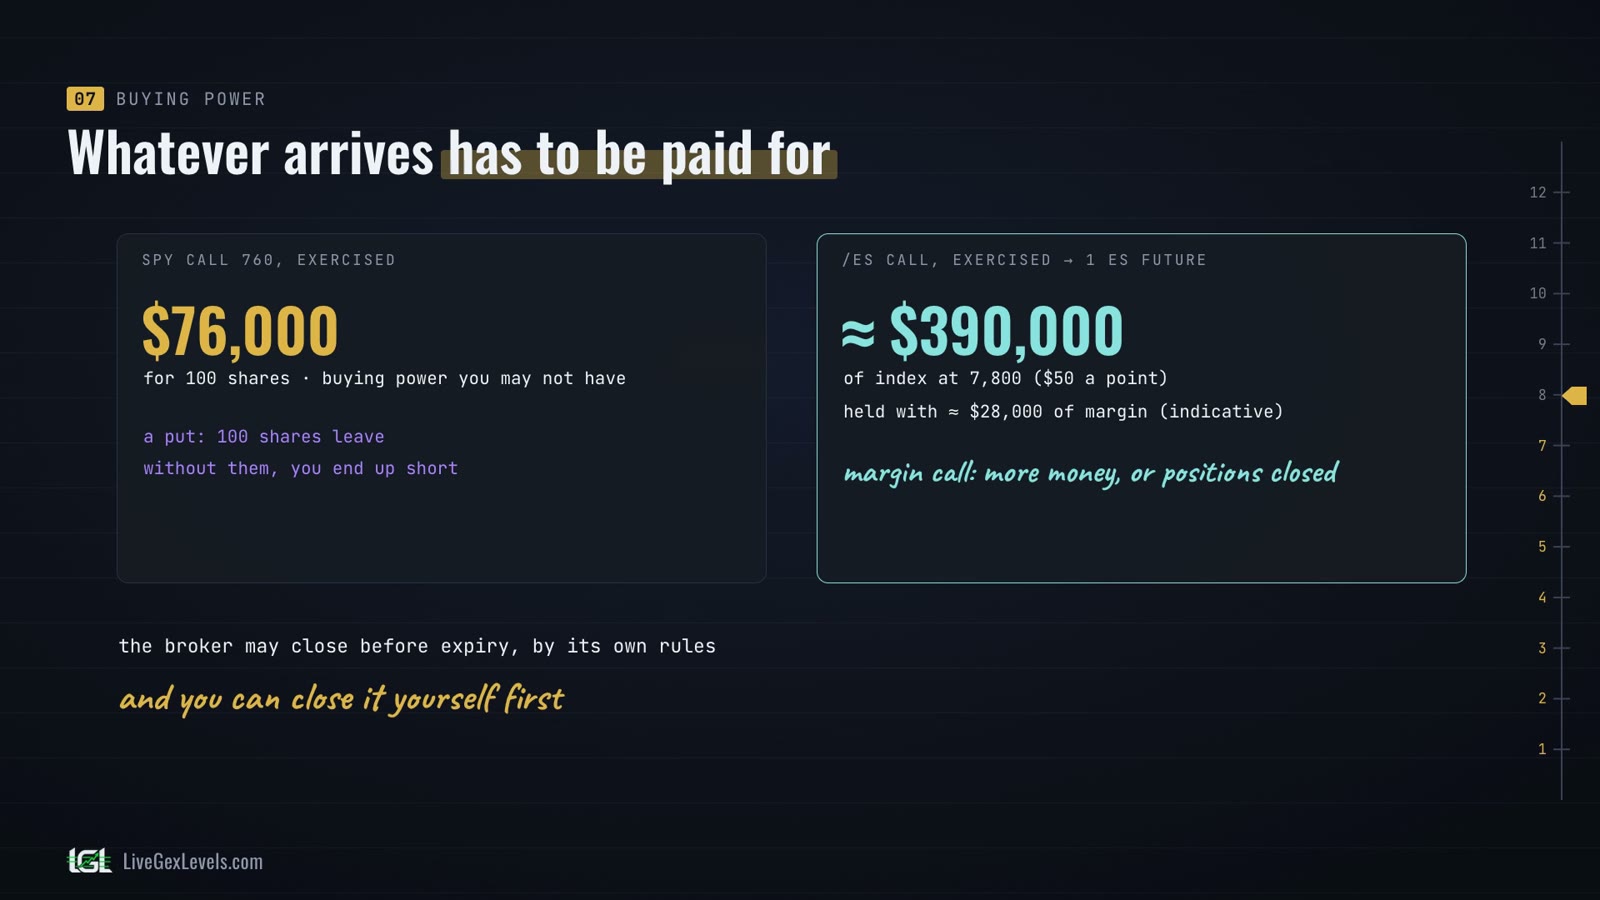
Shares, a future, goods: whatever arrives has to be paid for, or covered with margin. That's the buying power risk. Exercise the SPY call at 760, or let it be exercised, and you pay 76,000 dollars for the shares: buying power you may not have.
With a put it works the other way: 100 shares leave your account, and if you don't hold them, you end up short.
Options on the ES future tell the same story, only bigger. An exercised call becomes one ES future: about 390,000 dollars of index at 7,800, held with about 28,000 dollars of margin. If the account can't carry it, a margin call follows: the broker asks for more money or closes positions, and it may close the position before expiry anyway. You can close it yourself first.
Early exercise and dividends
Closing first protects the buyer. The seller has a different risk: early assignment, and there's one moment when it's likely.
SPY pays a quarterly dividend to whoever owns the shares before the ex-dividend date. The holder of a call in the money may exercise the day before to collect it, and that pays when the dividend beats the time value left in the call. That's exactly when the seller can be assigned early.
Earnings are a different matter. Around the announcement the risk isn't early exercise: it's the price, which can gap, and implied volatility, which usually drops right after.
Automatic exercise
And if you do nothing? In the United States, on stocks, ETFs and indices, the clearing house, the OCC, exercises at expiry every option in the money by at least one cent: exercise by exception. If you don't want it, tell your broker before its cut-off time.
Each broker has its own rules: cut-off times, fees, positions closed early. Check them before expiry.
Options on /ES: style and offset
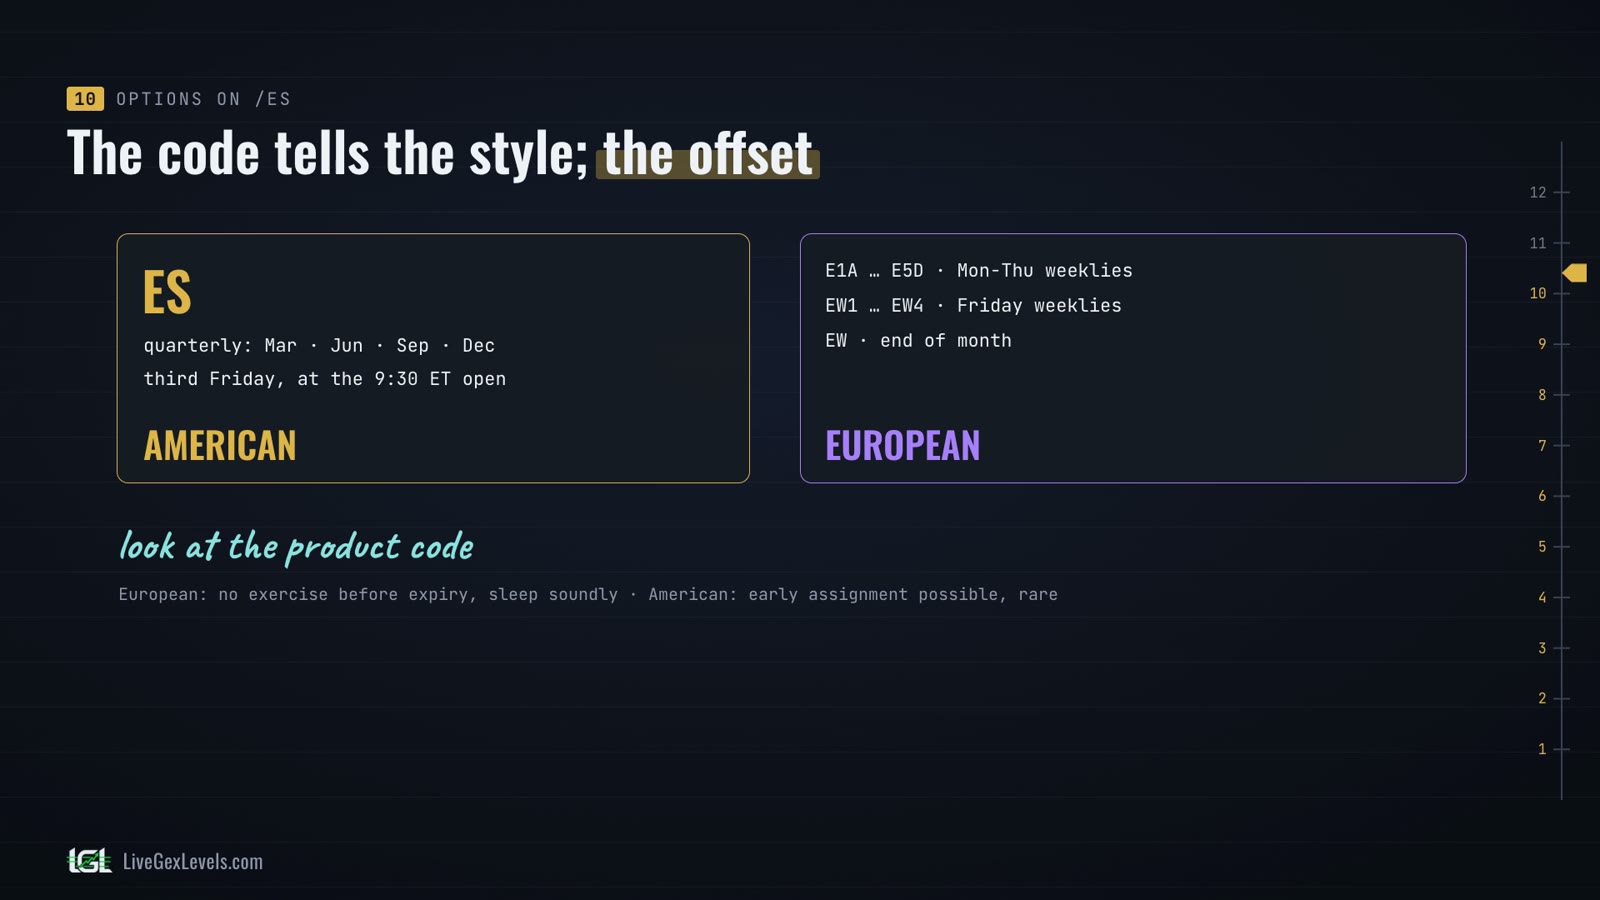
On options on the S&P 500 future, ES, the style depends on the expiry, and many get confused here. Only the quarterlies are American: March, June, September and December, expiring on the third Friday at the open. The weeklies, Monday to Friday, and the end of month are European.
The product code tells them apart: ES is the American quarterly; every other code is European. With a European option nobody can exercise before expiry, so early assignment isn't a concern until then. With an American quarterly, early assignment is possible, though rare.
At expiry an option in the money becomes a future. If you don't want it, open the opposite position and the two cancel out: on futures that's an offset, and the account ends flat. A long ES from a call: sell one ES. A short ES from a put: buy one.
A tip for the European ones: the outcome is decided by the fixing, a reference price for the future set at 3 pm Chicago time, 4 pm in New York. From then you know whether the future will arrive, though it reaches your account only overnight, so you can open the opposite position straight away: before the 4 pm pause, Chicago time, or when trading reopens at 5.
The limit: on the American quarterlies the outcome isn't certain until the evening processing. Open the opposite position and then get no future, and you're left holding an open future.
/MES: now settled in cash
One last, recent change. Since the end of June 2026, the new options on the micro S&P 500 future, MES, are European and settled in cash, like an index: no future arrives, and an option in the money pays the difference between the fixing and the strike, 5 dollars a point. Before, they delivered a future, like ES.
In brief
- In, at or out of the money compares the strike with the price: the same strike can be in for the call and out for the put.
- Before expiry, selling almost always gets you more than exercising: exercising throws the time value away.
- Options on stocks and SPY deliver 100 shares, index options pay cash, futures options one future, and a commodity future can bring the goods.
- Whatever arrives needs buying power, and a sold call can be assigned early before a dividend.
- At expiry, check your broker's rules, or close before.
Sources
- OCC — equity options product specifications
- CME Group: E-mini S&P 500 options contract specifications
- CME Group: FAQ on the Micro E-mini S&P 500 and Nasdaq-100 options
- tastytrade: pricing and fees
- Charles Schwab: pricing and fees
- Interactive Brokers: options commissions
- The Globe and Mail, 19 July 2010: How a hot cocoa play left trader holding the bag
More from this series
Read next
See the levels live
Seeing where dealers have to hedge is information a chart alone doesn't give you. Your edge starts with preparation.
Card required; after the trial the subscription renews at the launch price. For educational purposes only, not financial advice.
