
Options School · Published
The short put: selling insurance after a fall
After a few days of falling prices, some buy the underlying directly. Others sell a put. Why? Because fear raises the price of insurance, and whoever sells a put is the insurer: if the index bounces, three forces play for them; if the fall goes on, price and volatility play against them, and only time stays on their side.
 Watch on YouTube · 9:44
The other side of the put
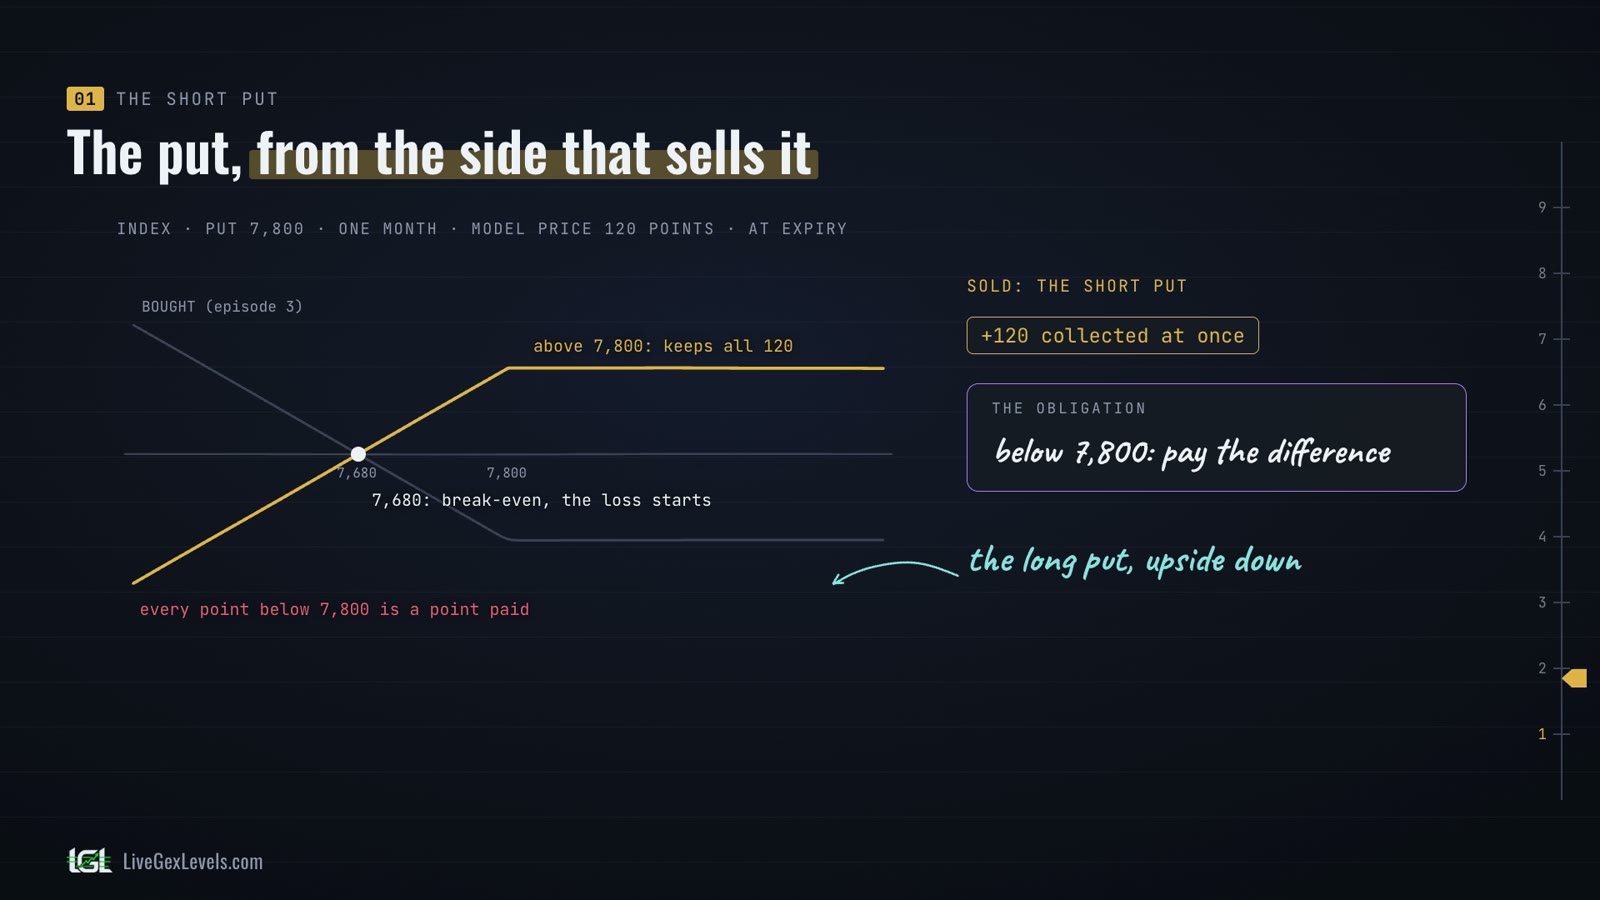
In the third episode we bought a put on the index: strike 7,800, a month out, for 120 points. Now look at it from the other side. Whoever sells it collects those 120 points straight away, and takes on an obligation: if the index ends below the strike, they pay the difference. That's the short put.
Above 7,800 the put expires worthless and the seller keeps everything. Below it, every point the index falls is a point the seller pays: at 7,680 they're back to zero, and further down the loss keeps growing. At expiry it's the long put upside down. And, as we said in the last episode, it's the same shape as the covered call.
Every number in the examples comes from a model, not from market quotes, costs aside; the historical cases come from the sources at the end.
Why after a fall
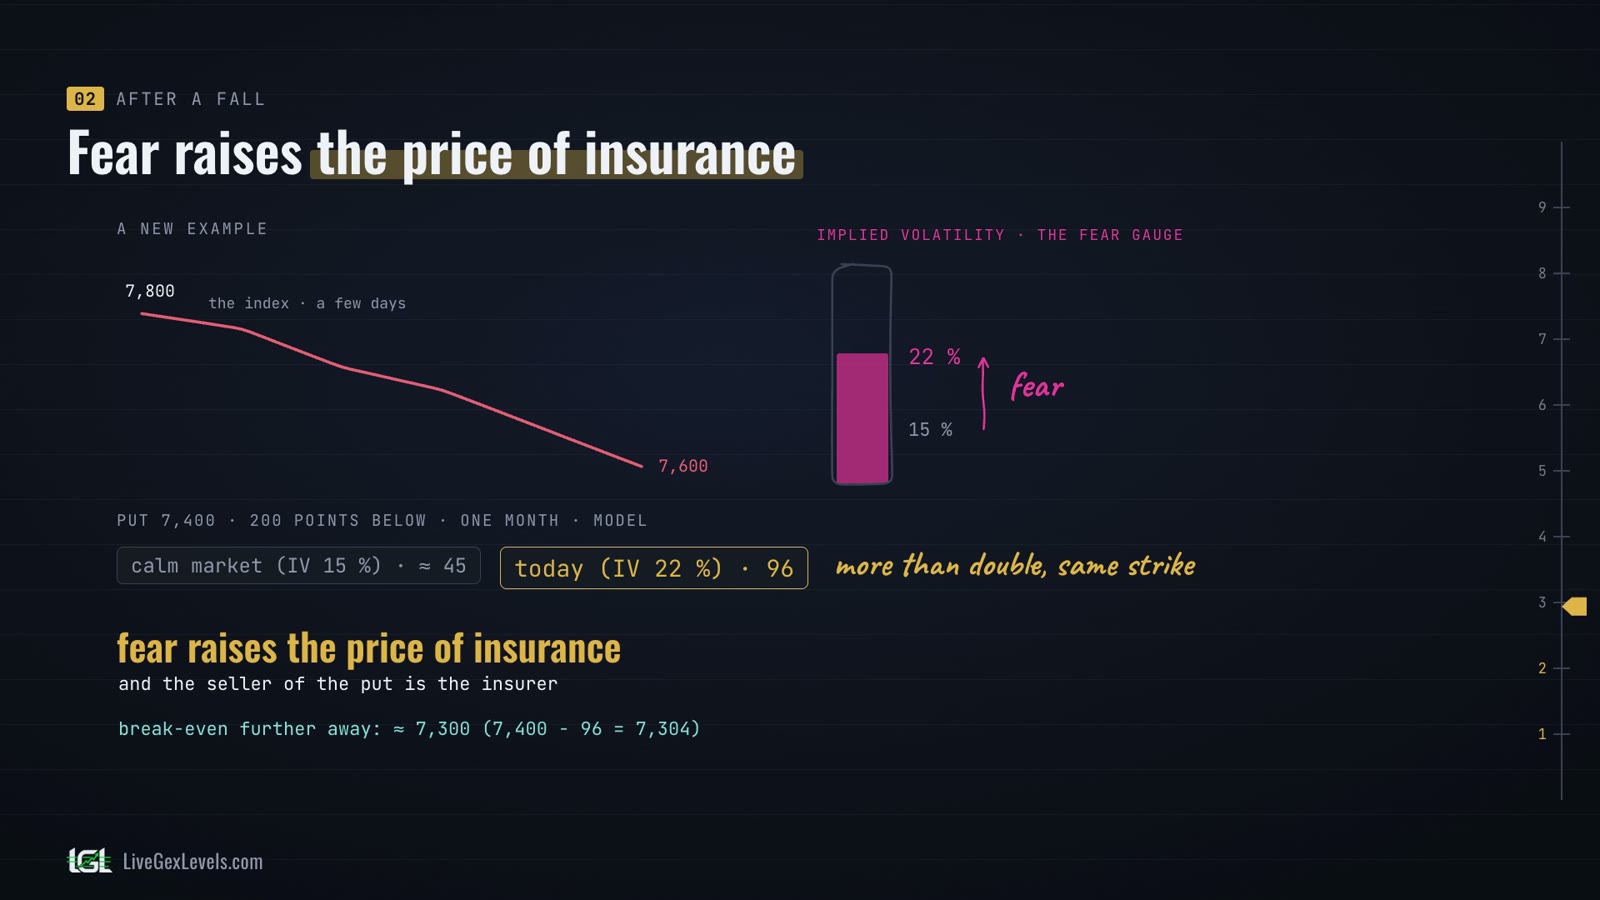
Now a new example. In a few days the index has fallen from 7,800 to 7,600, and fear has pushed implied volatility from 15 to 22 percent. Take the put with strike 7,400, two hundred points below, a month out.
In a calm market it would pay about 45 points. Today it pays 96: more than double, for the same strike. Fear raises the price of insurance, and whoever sells the put is the insurer. And the break-even moves further away, to about 7,300: the strike minus the premium.
A symphony
Here's what makes the short put special. Whoever sold it wants the put to lose value, and three forces act on its price: the greeks already met in this series.
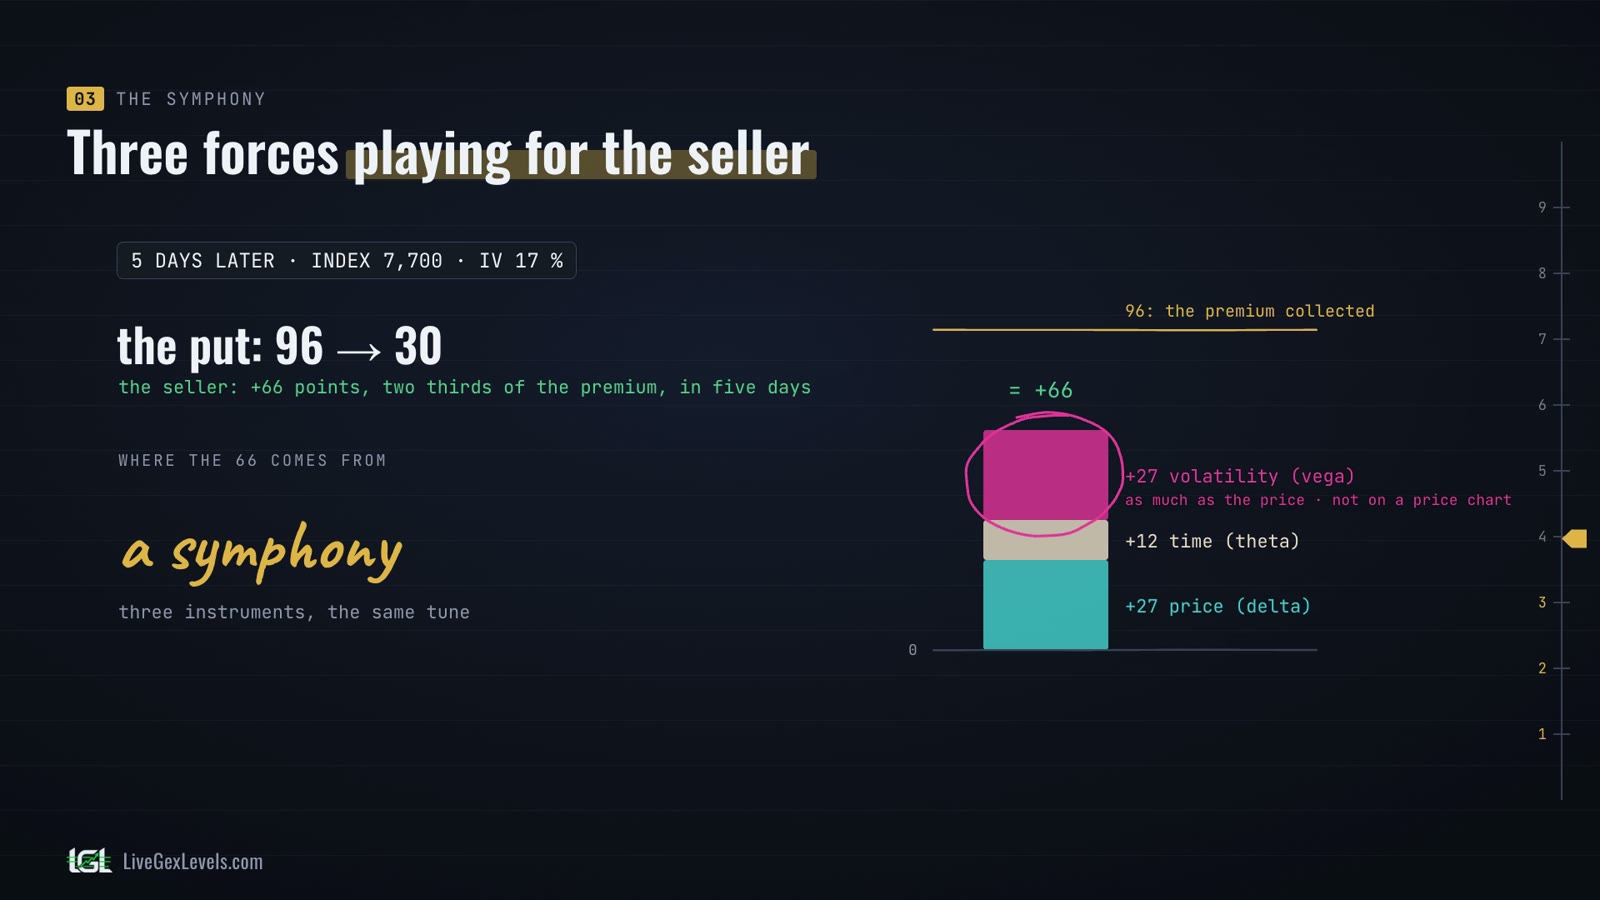
Delta: the index rises, and the put loses value. Theta: every day that passes, it loses a little more. Vega: fear calms down, implied volatility falls, and the put loses again. For the seller, vega is negative: it's implied volatility falling that makes them gain. Every loss of the put is a gain for whoever sold it, and on the index, prices rising and fear falling usually come together.
Let's play it. Five days later the index bounces to 7,700, and implied volatility drops to 17 percent. The put sold for 96 is now worth 30: the seller is up 66 points, two thirds of the premium, in five days. Where does it come from? About 27 from the price, 12 from time and 27 from volatility. Three instruments playing the same tune: a symphony.
And notice volatility: it counts as much as the price, and you don't see it on a price chart.
The symphony in reverse
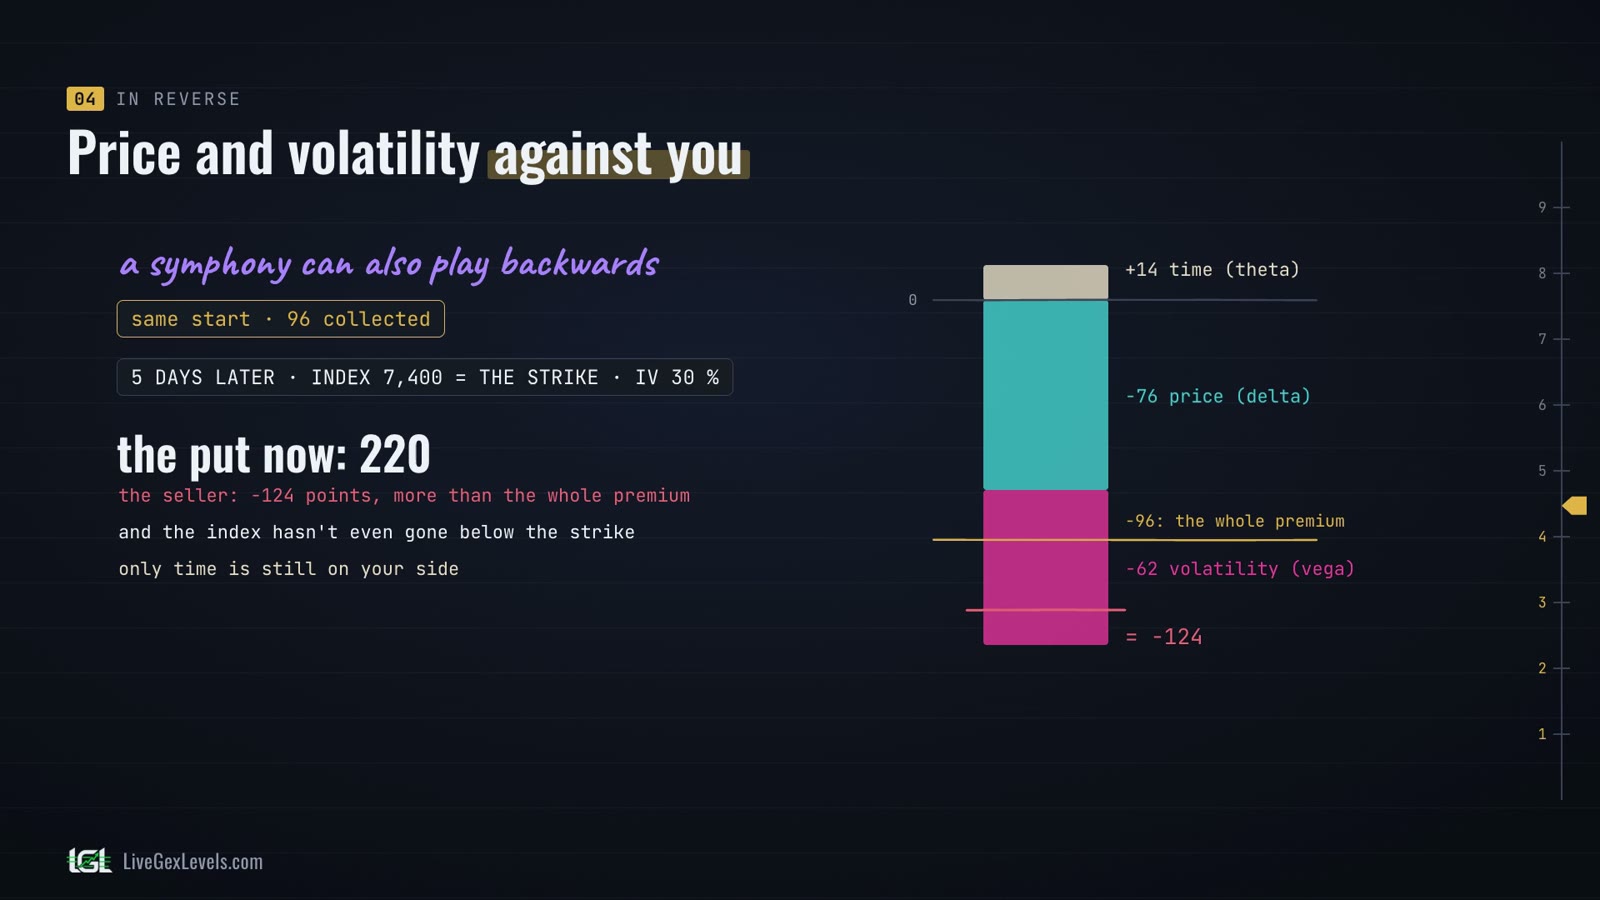
But a symphony can also play backwards, and that's why the short put is frightening. Same start, but the fall goes on: five days later the index is at 7,400, right on the strike, and implied volatility is at 30 percent. The put is now worth 220. The seller is down 124 points, more than the whole premium, and the index hasn't even gone below the strike. Price and volatility both work against you; only time is still on your side.
And there's a fourth force, gamma: the closer the index gets to the strike, the faster the put's delta grows against you. Meanwhile the broker raises the margin it asks for, because the margin grows as the index falls and as volatility rises: a margin call can arrive before the strike is ever touched.
It has happened for real. In February 2018 a fund that sold options on S&P 500 futures, puts and calls far from the price, lost more than four fifths of its capital in two days, as the market fell and volatility soared. It was closed.
The premium isn't yours yet
The broker credits the premium at once. Is it yours? Not yet. Right after the sale your result is zero: you've collected 96 points, and you owe a put worth 96. Every day the broker values that put at its market price, and how much of the premium you keep depends on where the index ends at expiry, or on what the put costs when you buy it back.
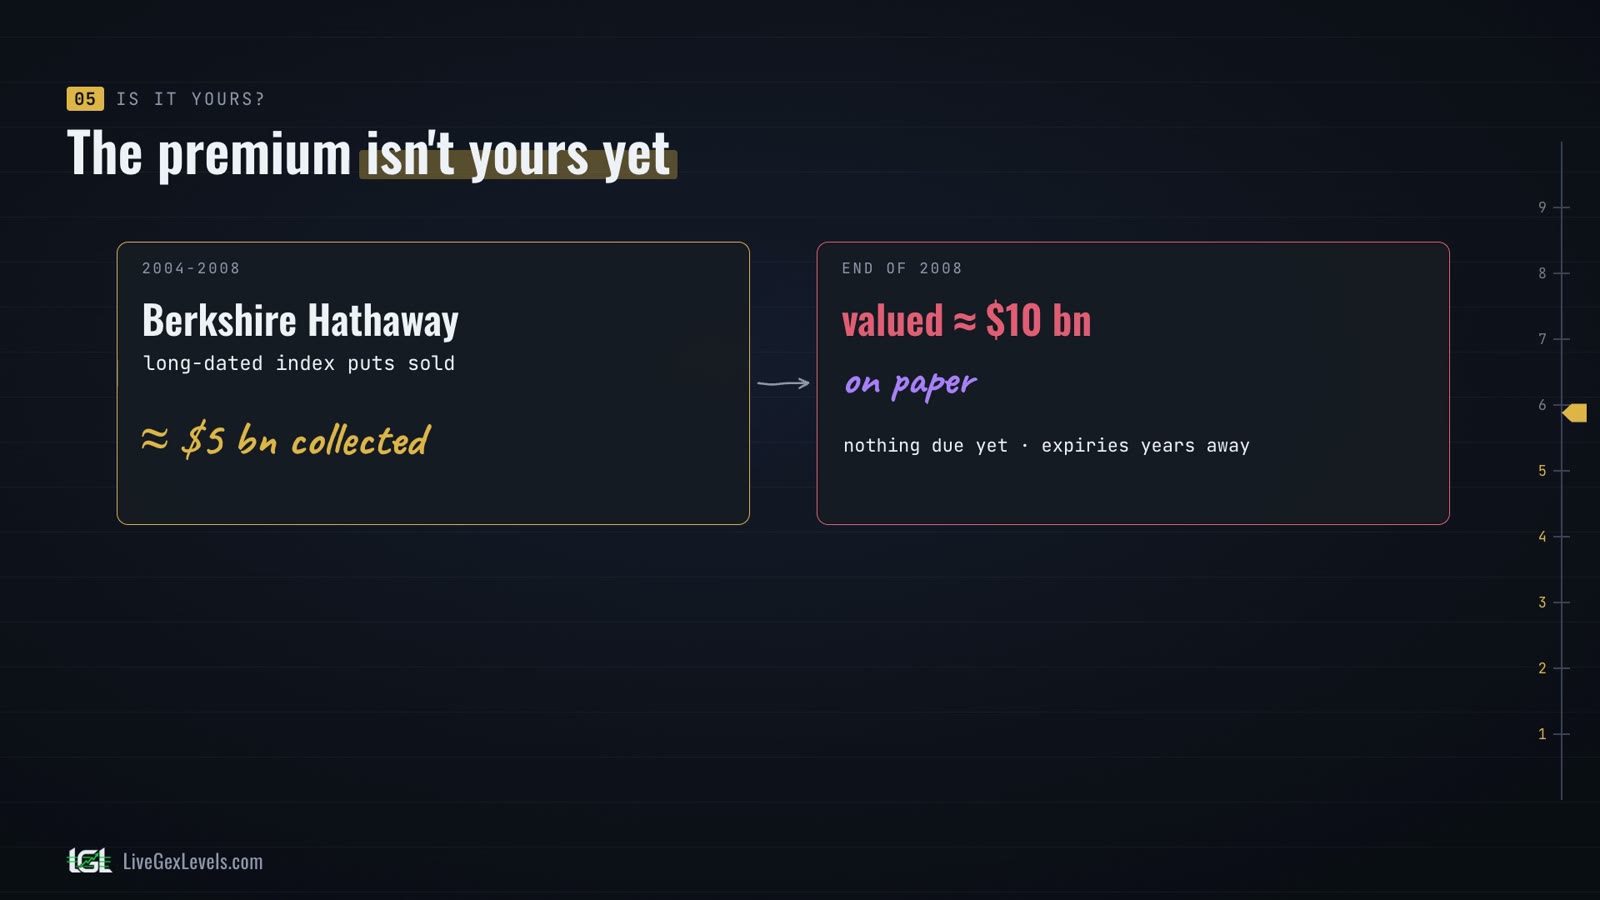
Even the best-known investors have been through it. Between 2004 and 2008, Warren Buffett's Berkshire Hathaway sold long-dated puts on stock indices and collected about five billion dollars. At the end of 2008, with markets down sharply, those puts were valued at about ten billion: on paper, a loss as large as the whole premium. Nothing had to be paid yet: the expiries were still many years away. The premium was in the account, but it wasn't yet theirs.
Large, but finite
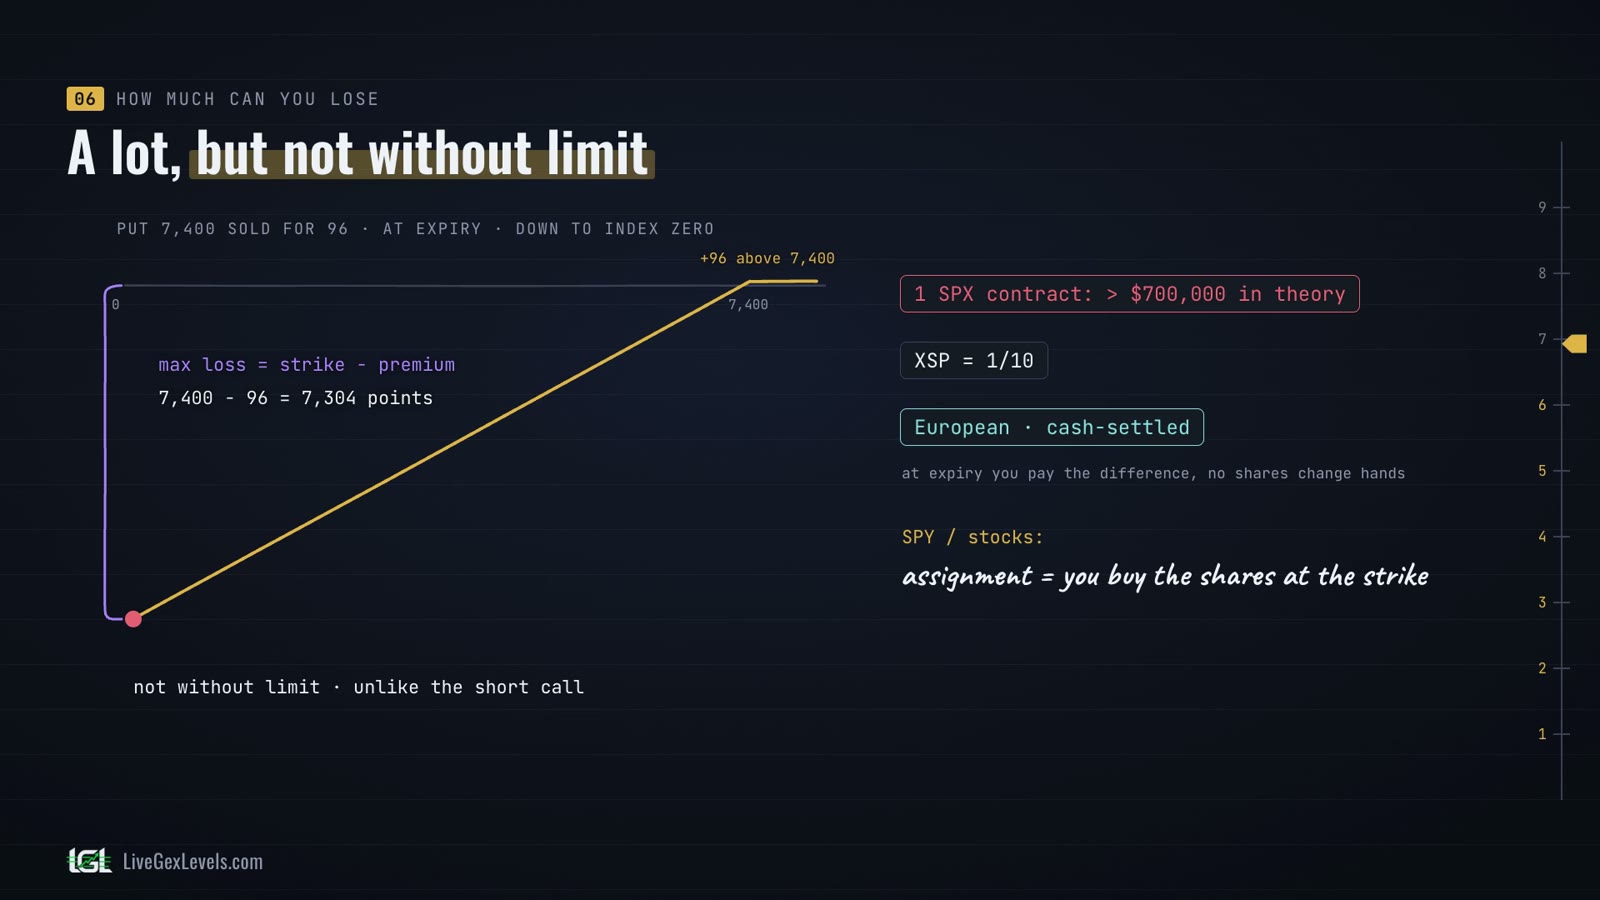
How much can you lose? A lot, but not without limit, unlike the uncovered short call. In the worst case the index goes to zero, and you lose the strike minus the premium: on the put at 7,400 sold for 96, 7,304 points. On one SPX contract that's, in theory, over seven hundred thousand dollars. XSP, the mini version, is one tenth.
Both are European and settled in cash: at expiry you pay the difference, and no shares change hands. On SPY or on a stock, instead, if you're assigned you buy the shares at the strike.
The investors' version
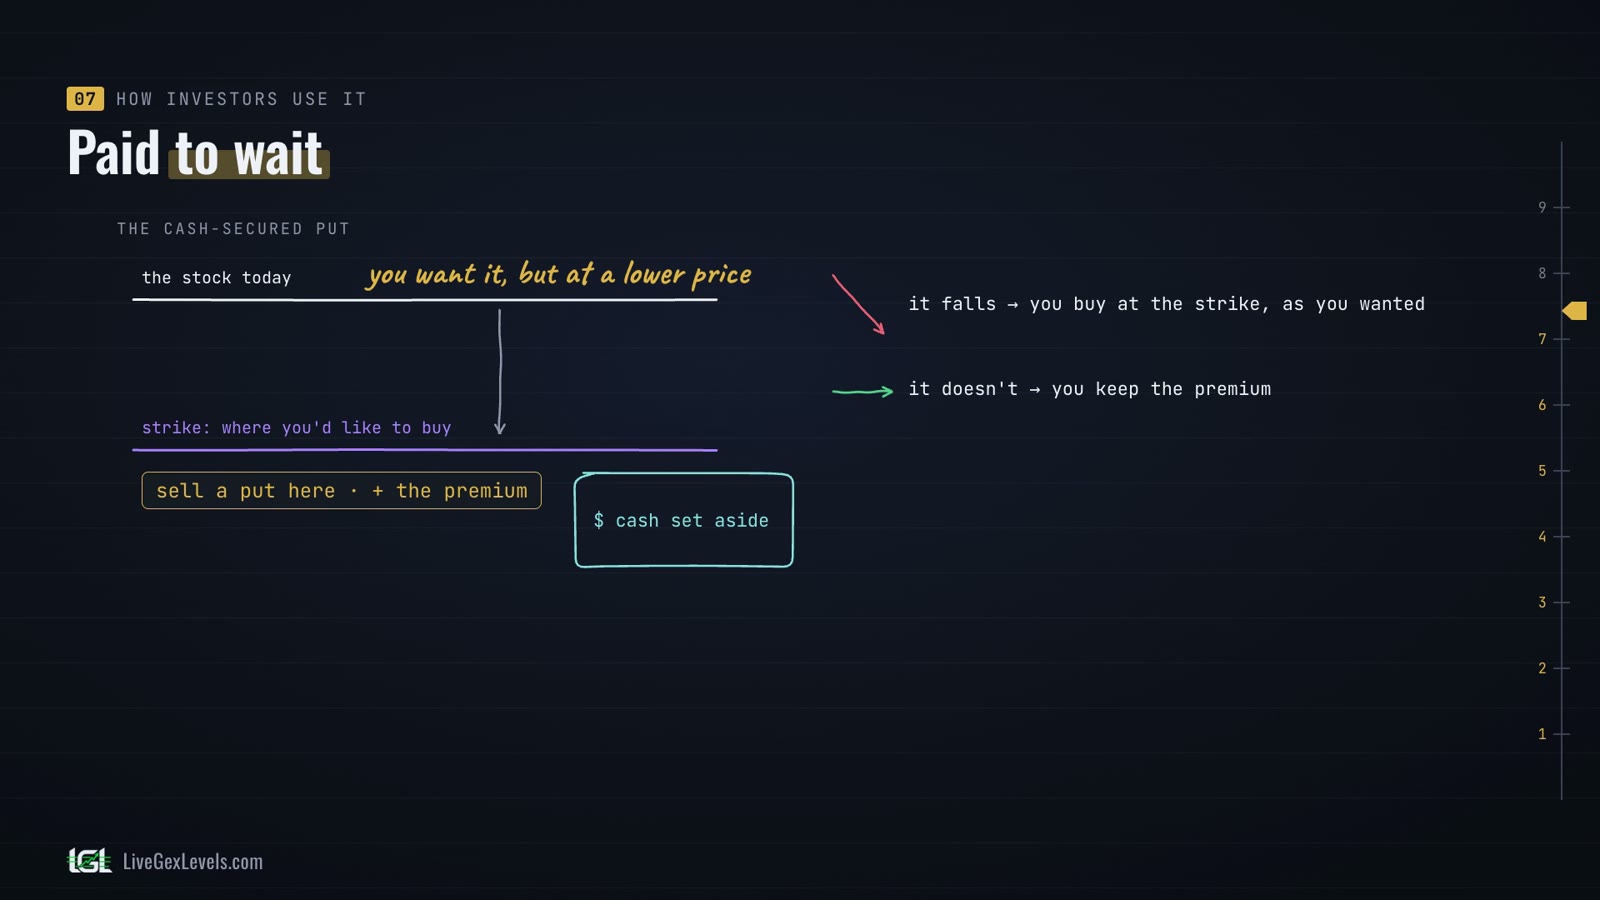
That's exactly how many investors use it. You want to buy a stock, but at a lower price. You sell a put with the strike where you'd like to buy, keeping the cash aside: it's called a cash-secured put. If the stock ends below the strike, you buy it there, as you wanted, even if by then it's worth less; if it doesn't, you keep the premium. You're paid to wait.
Warren Buffett told his shareholders, at the 1994 annual meeting, that he had sold puts on Coca-Cola shares this way: the price didn't fall, and Berkshire kept about seven and a half million dollars.
And on the S&P 500 there's even an official index that sells a put every month, the Cboe PutWrite: it comes up in the article on the two real edges in options.
The answer
Back to the opening question. Why do some sell a put after a fall? Because fear makes the premium richer, and if the index bounces, price, time and volatility all play for the seller.
On average, the fear priced into index options has been larger than the moves that followed: the article on the two real edges in options covers it. But the market pays more because it expects bigger moves, and sometimes they come: then the symphony plays in reverse.
In brief
- Selling a put means collecting the premium and taking on the obligation to pay below the strike.
- After a fall, fear makes the premium richer.
- If the index bounces, delta, theta and vega all work for the seller; if the fall goes on, delta and vega work against, gamma speeds it up, only theta still helps, and the margin rises.
- The maximum loss is large but finite: the strike minus the premium.
- The premium isn't yours yet: how much of it you keep depends on where the index ends at expiry, or on what the put costs when you buy it back.
- Every number in the examples comes from a model, costs aside.
Sources
- Berkshire Hathaway: 2008 letter to shareholders
- Berkshire Hathaway: 2010 letter to shareholders
- CNBC Warren Buffett Archive: 1994 Berkshire Hathaway annual meeting, afternoon session
- CFTC: press release 8392-21 (2021) on the fund of February 2018
- SEC: press release 2021-89 on the same fund
- Cboe: S&P 500 PutWrite Indices methodology
More from this series
Read next
See the levels live
Seeing where dealers have to hedge is information a chart alone doesn't give you. Your edge starts with preparation.
Card required; after the trial the subscription renews at the launch price. For educational purposes only, not financial advice.
